Insurance Company Compliance in India refers to the legal, financial, operational and regulatory requirements that insurance businesses must follow to operate lawfully. The Insurance Regulatory and Development Authority of India (IRDAI) supervises insurance companies, establishes regulatory standards and protects policyholders' interests. Insurance companies manage premiums, claims, investments and important customer information. Therefore, proper IRDAI Compliance is necessary to maintain financial stability, protect customers and ensure transparency in business operations.
In 2026, insurance businesses must also consider the changes introduced through the Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Act, 2025, along with existing IRDAI regulations and applicable circulars. Compliance Calendar LLP provides professional assistance with Insurance Company Compliance, IRDAI regulatory filings, Insurance Company Registration and ongoing compliance management.
What is Insurance Company Compliance?
Insurance Company Compliance means following the laws, rules and regulatory guidelines applicable to insurance businesses in India. These requirements cover company registration, financial reporting, policyholder protection, corporate governance, claims handling and regulatory filings. For example, an insurance company must maintain accurate records of premiums collected, claims settled and investments made. It must also ensure that customer information remains secure and insurance claims are handled according to applicable rules. Compliance is a continuous responsibility that helps insurance companies operate responsibly and avoid unnecessary regulatory problems.
Why is Insurance Regulatory Compliance Important?
Insurance companies collect premiums from policyholders and provide financial protection against future risks. Proper compliance helps ensure that companies have sufficient financial resources to meet these obligations. A strong compliance system also improves transparency, identifies operational risks and helps prevent errors in financial reporting and claims management. It builds confidence among customers, investors and regulatory authorities.
IRDAI Regulations and Insurance Laws
Legal Framework for Insurance Companies
Insurance companies in India must follow various laws, rules and regulations to operate legally and protect the interests of policyholders. The Insurance Regulatory and Development Authority of India (IRDAI) is the primary regulatory authority responsible for supervising insurance businesses, issuing registrations, monitoring financial stability and ensuring fair treatment of customers. Every life insurance, general insurance, health insurance and reinsurance company must comply with the applicable legal requirements.
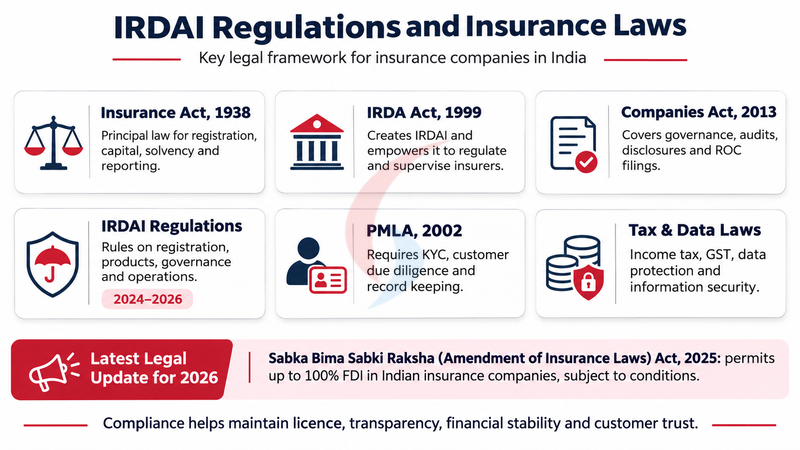
The major laws and regulations governing insurance companies in India include:
-
Insurance Act, 1938: This is the principal legislation regulating insurance businesses in India. It covers insurance company registration, capital requirements, solvency, investments, financial reporting and other statutory obligations.
-
IRDA Act, 1999: This Act establishes IRDAI and gives it the authority to regulate, supervise and promote the insurance industry. IRDAI monitors insurers, protects policyholder interests and takes regulatory action against non-compliant companies.
-
Companies Act, 2013: Insurance companies incorporated under this Act must comply with applicable corporate governance, board management, statutory audit, financial disclosure and ROC filing requirements.
-
IRDAI Regulations, 2024–2026: These regulations cover insurance company registration, capital structure, corporate governance, insurance products, policyholder protection and operational compliance. The 2026 amendments also introduced changes relating to registration and share transfers.
-
Prevention of Money Laundering Act, 2002 (PMLA): Insurance companies must follow applicable anti-money laundering requirements, conduct customer due diligence, maintain prescribed records and report specified transactions to the relevant authorities.
-
Taxation and Data Protection Laws: Insurance companies must comply with applicable income tax, GST, data protection and information security requirements while maintaining financial records and protecting customer information.
-
Latest Legal Update for 2026: The Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Act, 2025 introduced significant changes to India's insurance laws, including permitting up to 100% foreign direct investment in Indian insurance companies, subject to applicable conditions. These reforms aim to attract investment, strengthen regulatory supervision and improve insurance accessibility.
Compliance with these laws is essential not only for obtaining IRDAI registration but also for maintaining an insurance company's licence, financial stability, transparency and customer trust. Non-compliance may result in regulatory penalties, restrictions on business operations or other action by IRDAI.
Important IRDAI Regulatory Requirements
Registration and Capital Requirements: Insurance companies must obtain the necessary authorization from IRDAI before commencing regulated insurance business. They must also satisfy prescribed capital, ownership and promoter eligibility conditions to demonstrate their financial capability.
Corporate Governance Requirements: IRDAI requires insurers to establish appropriate management and governance systems. These include board oversight, internal controls, governance committees and accountability for regulatory compliance.
Policyholder Protection Requirements: Insurance companies must provide accurate policy information and maintain transparent procedures for claims settlement and customer complaints. These requirements help protect customers from unfair practices and inadequate services.
Financial and Investment Regulations: IRDAI regulates the management of insurer funds, financial statements, investment activities and solvency. These requirements help ensure that insurers can meet future claims and other financial obligations.
Important Insurance Law Changes in 2026
The Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Act, 2025, with substantial provisions effective from 5 February 2026, introduced several important changes. The amendment increased the foreign investment limit in Indian insurance companies from 74% to 100%, subject to applicable conditions. It also reduced the net owned funds requirement for foreign reinsurers from Rs.5,000 crore to Rs.1,000 crore.
Additionally, the amendments changed certain regulatory approval requirements and strengthened IRDAI's enforcement powers. Insurance businesses should review the revised provisions and applicable notifications to understand how these changes affect their operations.
Compliance Checklist for Insurance Companies
What is an IRDAI Compliance Checklist?
An IRDAI Compliance Checklist is a structured record of the legal, financial and regulatory obligations applicable to an insurance company. It helps compliance teams identify required filings, monitor deadlines and ensure that important regulatory responsibilities are assigned to the appropriate employees.
Important Compliance Areas
|
Compliance Area
|
Requirements
|
|
IRDAI Registration
|
Maintain the required regulatory authorization
|
|
Corporate Governance
|
Board oversight, committees and governance disclosures
|
|
Financial Compliance
|
Financial statements, actuarial reporting and solvency
|
|
Investment Compliance
|
Investment controls, limits and reporting
|
|
Regulatory Filings
|
Prescribed IRDAI and applicable MCA submissions
|
|
Policyholder Protection
|
Claims handling, servicing and grievance redressal
|
|
AML and KYC
|
Customer verification and transaction monitoring
|
|
Cybersecurity
|
Data security and applicable incident reporting
|
|
Internal Audit
|
Periodic reviews and corrective measures
|
|
Regulatory Updates
|
Review applicable amendments and circulars
|
Preparing a Compliance Calendar: An insurance company should maintain a compliance calendar covering monthly, quarterly, annual and event-based obligations. Each requirement should have a clear deadline, responsible person and completion status. This helps the organization monitor pending tasks and prepare required documents in advance.
Periodic Compliance Review: Regular compliance reviews help identify missing records, delayed filings, regulatory observations and weaknesses in internal controls. The compliance team should report significant findings to management and ensure that corrective actions are completed within the required timelines.
Consequences of Insurance Regulatory Non-Compliance: Non-compliance may result in regulatory directions, financial penalties, restrictions on business activities or other enforcement measures. Serious violations may affect an insurance company's regulatory authorization or ability to conduct business. Maintaining accurate records and addressing compliance issues promptly helps reduce regulatory and reputational risks.
Policyholder Protection and Customer Compliance
Protection of Policyholders' Interests: Policyholder protection is a major responsibility of insurance companies. Insurers must provide clear information about coverage, premiums, exclusions and important policy conditions. Customers should understand the benefits and limitations of insurance products before making purchasing decisions.
Claims Settlement Requirements: Insurance companies must maintain fair and transparent claims procedures. Claims should be registered, assessed and settled according to applicable policy terms and regulatory requirements. Timely communication helps customers understand the progress of their claims.
Customer Grievance Redressal: Insurance companies must establish procedures for receiving and resolving customer complaints. Complaints may relate to policy servicing, premium payments, claim delays or other insurance-related concerns. Policyholders may also use the applicable IRDAI grievance redressal mechanism, including Bima Bharosa, and approach the Insurance Ombudsman where eligible.
Customer Data Protection: Insurance companies collect personal, financial and medical information from customers. They must maintain appropriate data security controls and comply with applicable information security, cybersecurity and data protection requirements. Secure systems, limited access to customer records and proper incident management help reduce the risk of information misuse.
Insurance Company Registration Process
Step 1: Select the Insurance Business Category
The applicant must first decide whether the proposed company will operate in life insurance, general insurance, health insurance or reinsurance. This decision determines the regulatory requirements applicable to the business.
Step 2: Prepare the Required Documents
The applicant must prepare information regarding promoters, ownership structure, capital, business plans and financial projections. These documents help IRDAI evaluate the proposed insurance business.
Step 3: Submit the Registration Application
The application is submitted through the prescribed IRDAI procedure along with the necessary supporting documents and applicable fees.
Step 4: Regulatory Review and Verification
IRDAI examines the application and may request additional records or clarifications. The review focuses on whether the applicant satisfies the prescribed requirements.
Step 5: Obtain IRDAI Registration
If IRDAI is satisfied with the application and supporting information, it may grant the required registration. The company can undertake permitted insurance business only after obtaining the necessary authorization.
Major IRDAI Compliance Requirements
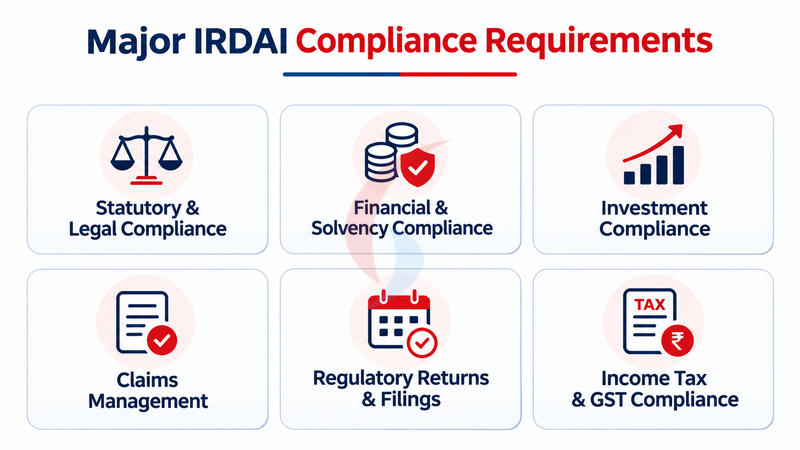
Insurance companies in India must follow various legal, financial and regulatory requirements prescribed by IRDAI and other applicable authorities. These compliances help maintain financial stability, protect policyholders and ensure transparent business operations.
Statutory and Legal Compliance: Insurance companies must comply with the Insurance Act, 1938, IRDAI regulations and applicable provisions of the Companies Act, 2013. This includes maintaining statutory records, obtaining necessary approvals, conducting board meetings and completing required MCA filings.
Financial and Solvency Compliance: Insurers must maintain sufficient capital and the prescribed solvency margin to meet policyholder obligations. They must regularly assess financial liabilities, maintain adequate reserves and prepare financial reports. Actuarial assessments help evaluate the company's financial stability.
Investment Compliance: IRDAI regulates how insurance companies invest their funds. Insurers must follow prescribed investment limits, monitor portfolio risks and maintain proper investment records to ensure responsible financial management.
Claims Management Compliance: Insurance companies must maintain transparent procedures for receiving, evaluating and settling claims. Claims should be processed according to policy terms and regulatory guidelines, with proper documentation and timely communication to policyholders.
Annual Financial Reporting and Audit: Insurance companies must prepare annual financial statements covering premiums, claims, investments, reserves, assets and liabilities. Statutory audits and actuarial reporting help ensure financial accuracy and compliance with applicable regulatory requirements.
IRDAI Regulatory Returns and Filings: Insurers must submit prescribed regulatory returns within the applicable deadlines. These reports help IRDAI monitor financial performance, solvency, investments and governance.
|
Filing Type
|
Compliance Requirements
|
|
Monthly/Quarterly
|
Financial, investment, solvency and business returns, as applicable
|
|
Half-Yearly
|
Selected financial and governance disclosures
|
|
Annual
|
Audited financial statements, actuarial reports and compliance certifications
|
|
Event-Based
|
Management changes, share transfers and other reportable events
|
Income Tax and GST Compliance: Insurance companies must comply with applicable income-tax, TDS and GST requirements. Proper tax records, timely return filing and regular review of taxation changes help prevent penalties and reporting errors. The exact compliance requirements and filing deadlines depend on the insurer's business category and applicable IRDAI regulations.
What is Risk Management in Insurance Companies?
Risk Management is an important part of Insurance Company Compliance in India. Insurance companies face different risks, including financial losses, claim uncertainties, investment risks, operational failures and cybersecurity threats. IRDAI requires insurers to establish appropriate risk management systems to identify, assess and control these risks.
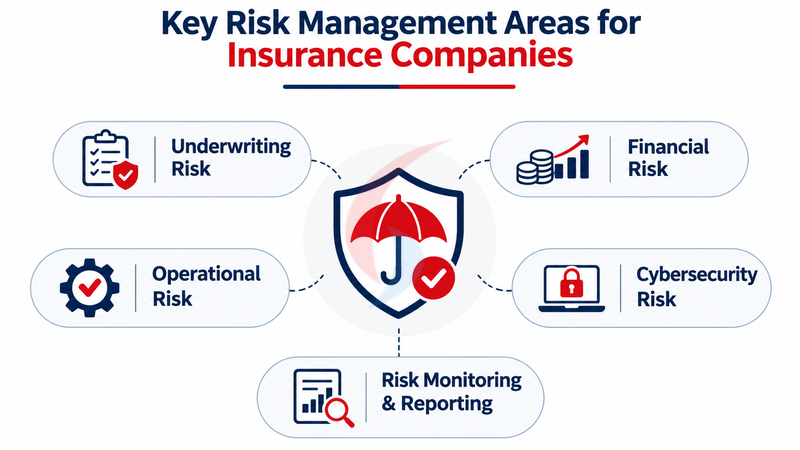
Key Risk Management Requirements
-
Underwriting Risk: Insurance companies must evaluate the risks associated with issuing insurance policies. Proper underwriting helps insurers determine suitable premiums and manage potential claim liabilities.
-
Financial Risk: Insurers must monitor their financial position, investments and solvency requirements to ensure they have sufficient funds to meet policyholder obligations.
-
Operational Risk: Companies should maintain internal controls to reduce errors, fraud, system failures and operational disruptions that may affect business activities.
-
Cybersecurity Risk: Insurance companies must protect customer information and business systems against cyberattacks, unauthorized access and data breaches.
-
Risk Monitoring and Reporting: Insurers should regularly review their risk exposure, maintain appropriate records and report relevant risks to management, the board and IRDAI as required.
Corporate Governance Company Compliance
Corporate Governance Requirements: Corporate governance establishes how an insurance company is managed, controlled and supervised. IRDAI requires insurers to maintain appropriate governance arrangements to ensure that management decisions are transparent and consistent with regulatory obligations.
Role of the Board of Directors: The board of directors is responsible for overseeing the company's business strategy, financial stability, risk management and regulatory compliance. Board members must ensure that adequate internal controls are maintained and important regulatory matters receive proper attention.
Important Board Committees: Insurance companies must maintain applicable governance committees according to IRDAI requirements.
Audit Committee: Reviews financial reporting, audit findings and internal control issues. It helps identify weaknesses in accounting and compliance systems.
Risk Management Committee: Monitors important business risks and reviews the company's risk management arrangements.
Investment Committee: Oversees investment policies, portfolio risks and compliance with applicable investment regulations.
Policyholder Protection Committee: Reviews matter concerning customer service, grievances, claims-related issues and policyholder interests.
Compliance Officer and Management Responsibilities: The compliance function helps the organization identify regulatory obligations, monitor filings and report compliance matters to management. Relevant key management personnel must perform their prescribed responsibilities and maintain the required standards of suitability and professional competence.
Internal Audit and Risk Management: Internal audits examine whether company policies, financial controls and compliance procedures are working effectively. Insurance companies must also manage underwriting, investment, liquidity, operational and cybersecurity risks. Regular assessments help identify problems and support corrective action.
Why Choose Compliance Calendar LLP?
Professional IRDAI Compliance Consultancy
Compliance Calendar LLP provides professional assistance with Insurance Company Compliance, IRDAI Compliance Requirements, Insurance Company Registration and regulatory filings in India. Our team helps businesses understand applicable legal requirements, prepare regulatory documentation and organize statutory compliance obligations. We focus on providing clear guidance and supporting accurate documentation so that companies can manage their compliance responsibilities more effectively.
With changing insurance industry regulations, companies must regularly review their financial, operational and governance-related compliance requirements. Compliance Calendar LLP assists with regulatory applicability assessments, compliance checklists, documentation, filing coordination and responses to regulatory queries. Our objective is to help insurance businesses establish organized compliance processes and reduce avoidable filing errors and delays.
Get in touch with Compliance Calendar LLP today!
Call/WhatsApp: +91 9988424211
Email: info@ccoffice.in


 Compliance Calendar ®