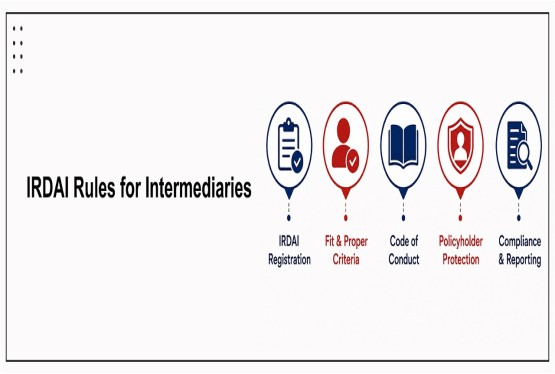

The Insurance Regulatory and Development Authority of India (IRDAI) has introduced significant changes to the regulatory framework governing insurance intermediaries, including Insurance Marketing Firms (IMFs).
The reforms are part of the wider regulatory transition following the Sabka Bima, Sabki Raksha (Amendment of Insurance Laws) Act, 2025, and are aimed at simplifying the registration framework, strengthening compliance, improving accountability and enhancing protection for policyholders. The proposed amendments specifically cover the IRDAI framework for Insurance Marketing Firms along with other insurance intermediaries.
The most important change for IMFs is the move away from the traditional three-year renewal model towards continuing/perpetual registration subject to payment of an annual fee.
Three-Year Renewal System to be Replaced
Under the existing, an IMF's Certificate of Registration (CoR) was generally issued for a specified period and required renewal. The new framework moves towards a system where registration will continue to remain valid, subject to the IMF fulfilling the applicable regulatory requirements, particularly payment of the prescribed annual fee.
In other words, the focus is shifting from periodic renewal to continuous regulatory compliance. This is expected to reduce repetitive renewal-related documentation and make the regulatory process easier for compliant IMFs.
Introduction of Annual Fee System
One of the most significant changes is the introduction of an annual fee mechanism. Instead of paying a renewal fee after every three years, an IMF will be required to pay an annual fee for every financial year.
As proposed in the 2026 framework, the annual fee for an IMF is the higher of:
-
Rs.10,000, or
-
1/25th of 1% of commission and other receipts from insurers during the preceding financial year, rounded to the next thousand.
Therefore, IMFs will need to maintain proper financial records and monitor their annual regulatory fee liability on an ongoing basis.
Example
If the applicable calculation based on commission and other receipts results in an amount lower than Rs.10,000, the minimum annual fee would remain Rs.10,000.
If the calculated amount exceeds Rs.10,000, the higher amount would become payable.
Existing IMFs Will Need to Transition to the New Certificate Framework
Existing IMFs holding a valid registration under the earlier regime will have to transition to the revised framework and obtain the applicable fresh Certificate of Registration as prescribed under the transitional provisions.
Therefore, existing IMFs should not assume that the abolition of periodic renewal means that no action is required. They should monitor the applicable transition timeline and ensure that the required application, documentation and annual fee are completed within the prescribed period.
Late Payment of Annual Fee
The new framework also introduces consequences for delayed payment of the annual fee.
As proposed for IMFs:
-
Payment within 30 days after the due date may attract an additional fee of 2% of the annual fee.
-
Payment after 30 days but before the end of the relevant financial year may attract an additional fee of 10% of the annual fee.
-
Failure to pay within the relevant financial year may result in suspension or cancellation of the Certificate of Registration.
This makes timely payment an important annual compliance requirement for every IMF.
Registration Becomes Linked to Payment of Annual Fee
Under the revised approach, payment of the prescribed annual fee becomes an important condition for the continuation of registration. The proposed revised Certificate of Registration states that registration will remain in force subject to payment of the annual fee, until the registration is surrendered, suspended or cancelled by the Authority.
This effectively changes the compliance philosophy from: “Renew every three years” to “Maintain registration continuously through annual compliance.”
Electronic Payment of Fees
The revised framework also moves towards electronic payment of application and annual fees. This is consistent with IRDAI's broader objective of simplifying regulatory processes and reducing manual compliance.
IMFs should therefore ensure that the applicable fees are paid through the prescribed electronic mode and maintain proper payment records for their compliance files.
Stronger Consequences for Non-Compliance
The new framework gives greater importance to continuous compliance.
Failure to pay the annual fee within the prescribed period can expose an IMF to regulatory action, including suspension or cancellation of registration.
Accordingly, IMFs should introduce an internal compliance calendar covering:
-
Annual fee payment
-
Regulatory filings
-
Principal Officer requirements
-
Insurance Sales Person compliance
-
Training requirements
-
Professional indemnity insurance
-
Record maintenance
-
Regulatory disclosures
Continuous Learning and Training Requirements
The new regulatory approach places greater emphasis on continuous professional development. The framework provides for ongoing training requirements for relevant personnel, with the objective of ensuring that persons involved in insurance solicitation and distribution remain updated with regulatory and insurance-sector developments.
This represents a shift from treating training as a one-time registration formality to viewing continuous learning as an ongoing compliance responsibility.
IRDAI's Power to Impose Additional Conditions
The amended framework also strengthens IRDAI's supervisory powers.
The Authority may impose additional conditions where considered necessary in the interest of:
-
Policyholders
-
Orderly development of the insurance business
-
Proper conduct of the IMF
-
Regulatory compliance
-
Protection against unfair or inappropriate sales practices
This gives IRDAI greater flexibility to address emerging risks and business practices within the intermediary sector.
New Certificate of Registration Format
A revised format of the Certificate of Registration (CoR) has been proposed under the new framework.
The certificate will reflect the new continuing-registration structure and will remain subject to applicable regulatory conditions and payment of the prescribed annual fee.
Duplicate Certificate Requirement Removed
The earlier requirement relating to a duplicate Certificate of Registration has been proposed to be removed. This is part of the broader effort to simplify documentation and reduce unnecessary procedural requirements.
Renewal Forms and Renewal-Based Compliance to be Removed
Since the regulatory model is moving towards continuing registration, the traditional renewal process and renewal-related forms are being removed/restructured. For IMFs, this means compliance will increasingly focus on annual fee payment and continuing regulatory obligations, rather than preparing a complete renewal application every few years.
Application and Annual Fees Through Recognised Electronic Modes
The revised provides for payment of applicable fees through recognised electronic payment mechanisms. For new IMF applicants, the proposed application fee is Rs.10,000, replacing the earlier Rs.5,000 application fee under the existing. Therefore, applicants planning a new IMF registration should also take the revised fee structure into account while budgeting for registration.
Registration Becomes Active After Payment of Prescribed Fee
A further important procedural change is that, after the Authority communicates the grant of registration, the applicant is required to pay the prescribed annual fee within the stipulated period. The registration is then granted/continued subject to payment of the applicable fee. This creates a direct connection between regulatory approval, fee payment and activation/continuation of the registration.
Use of “Insurance” or “Assurance” for IMF Associations
The proposed also provides an important naming-related change for associations or bodies of Insurance Marketing Firms. An association or body of IMFs may use the word “Insurance” or “Assurance” in its name to indicate the nature of its organisation and services, subject to the applicable regulatory conditions. This provision does not apply to individual Insurance Marketing Firms.
What These Changes Mean for Existing IMFs
The 2026 regulatory reforms represent a major shift in the compliance structure of Insurance Marketing Firms. The biggest practical change is that IMF registration is moving away from periodic renewal towards continuing registration with an annual compliance and fee obligation.
Existing IMFs should therefore:
-
Review the validity and status of their existing Certificate of Registration.
-
Track the transition requirements for the revised Certificate of Registration.
-
Calculate the applicable annual fee.
-
Maintain accurate commission and other receipt records.
-
Ensure timely payment of the annual fee.
-
Maintain Principal Officer and Insurance Sales Person compliance.
-
Monitor training and continuous learning requirements.
-
Maintain all statutory and regulatory records.
-
Ensure compliance with IRDAI directions and additional conditions.
-
Maintain a dedicated annual IMF compliance calendar.
Impact on New IMF Applicants
For entrepreneurs and entities planning to establish an Insurance Marketing Firm, the revised framework is significant. While the registration process is expected to become more streamlined due to the move away from periodic renewal, the emphasis on continuous compliance will increase.
A new IMF applicant should therefore plan not only for the initial registration but also for:
Annual regulatory fees
-
Principal Officer compliance
-
Insurance Sales Person requirements
-
Training and certification
-
Office and infrastructure requirements
-
Professional Indemnity Insurance
-
Regulatory records
-
Ongoing IRDAI compliance
The objective is to create a where an IMF can operate without repetitive renewal applications while ensuring that only active and compliant intermediaries continue to operate.
Conclusion
The IRDAI 2026 reforms for Insurance Marketing Firms mark a significant transformation in the regulatory framework. The move from a three-year renewal system to continuing registration, combined with an annual fee mechanism, stronger consequences for non-payment, electronic fee payment, enhanced supervisory powers and continuing compliance requirements, is expected to make the IMF regulatory framework more dynamic and accountability-driven.
For existing IMFs, the immediate priority should be to understand the applicable transition requirements and annual fee obligations. For new applicants, the revised framework may make the registration structure more convenient, but continuous regulatory compliance will become increasingly important. Overall, the reforms reflect IRDAI's broader objective of ease of doing business, stronger accountability, better regulatory oversight and enhanced protection of policyholders.
Regulatory Note: The June 2026 framework was issued initially as an exposure/consultation draft, and IRDAI subsequently approved intermediary reforms in July 2026. Therefore, before relying on specific dates, fee deadlines or transitional cut-off dates for an IMF, the final notified regulations and the latest IRDAI circulars should be checked. IRDAI had also extended transitional arrangements for annual-fee payment and issuance of Certificates of Registration beyond June 30, 2026 until notification of the relevant amended regulations.



















_learn_crop10_thumb.jpg)