
For a startup seeking investment, a strong product or business idea is only one part of the investment analysis. Investors may also want to understand what the startup actually owns or has the right to use, whether important intellectual assets are adequately protected, and whether unresolved IP issues could affect the business. This is why intellectual property can become an important part of investor due diligence.
Startup India identifies differentiation, competitive advantage, barriers to entry, imitation costs and potential exit avenues among investment considerations. Its funding guidance also states that angel networks and venture capital investors conduct due diligence before finalising an equity deal. IP can therefore be relevant to investment analysis, although its importance varies with the startup's sector, stage and business model.
1. What does an investor actually want to know?
The question is not simply whether the startup has a patent. An investor may want to know:
- What intellectual assets are essential to the business?
- Who owns them?
- Has ownership been documented?
- Does the startup have the necessary licences for third-party IP?
- Are there material conflicts or disputes?
- Has potentially patentable subject matter been disclosed too early?
- Are employee and contractor arrangements clear?
- Does the IP support the commercial claims made to investors?
- Could an IP problem materially affect revenue, operations or a future exit?
The precise scope of due diligence depends on the transaction and the risk profile of the business.
2. IP can support competitive advantage
A startup may differentiate itself through proprietary technology, a distinctive brand, product design, software, confidential know-how or a combination of these. Startup India's investor guidance specifically identifies differentiation, barriers to entry and imitation costs as relevant considerations and notes that patented ideas or products can demonstrate potential to investors.
This does not mean that every startup needs a patent portfolio. For some businesses, trademarks, copyright, confidential know-how, contracts or other commercial advantages may be more important. The relevant question is whether the startup has a defensible basis for its business not whether it possesses a particular type of IP registration.
3. Ownership is often the first IP due-diligence question
A startup may say that it owns its technology, but an investor may need evidence of that ownership. Consider a software startup whose application was initially developed by a founder before incorporation and later expanded by employees and freelancers.
The investor may need to determine:
- what was created before incorporation;
- who created it;
- what rights were transferred to the company;
- what was created by employees;
- what was created by contractors; and
- whether third-party material is
This is essentially a chain-of-title question. If ownership is unclear, the investor may need the issue resolved before treating the relevant IP as a clean company asset.
4. Founder-created IP does not automatically become company IP merely because a company is incorporated
Founders often create technology, content, designs or brands before incorporating the startup. Incorporation alone should not be treated as proof that every pre-incorporation IP right has automatically moved to the company.
Where appropriate, the company should have clear documentation showing an assignment or licence from the relevant founder or other owner. This becomes especially important when the IP is central to the company's value.
5. Employee-created IP requires careful analysis
Employees may create software, inventions, designs, documentation and other works during employment. The legal position is not identical for every category of IP. Statutory rules, the nature of the work, employment terms and the circumstances of creation may all matter.
Investors may therefore examine:
- employment agreements;
- IP ownership provisions;
- confidentiality clauses;
- invention-related documentation; and
- records concerning important
The objective is to determine the company's actual rights rather than assume that all employee-created material automatically belongs to the company or automatically belongs to the employee.
6. Freelancer and consultant arrangements can create hidden risk
Startups frequently outsource development, design, content creation and research. Payment for a service does not, by itself, answer every question about IP ownership.
An investor may examine whether the startup received an appropriate assignment or licence, whether the contract covers the relevant work, and whether the contractor had the necessary rights in third-party material. This is particularly important when a freelancer has created core source code, the principal brand identity or a key product design.
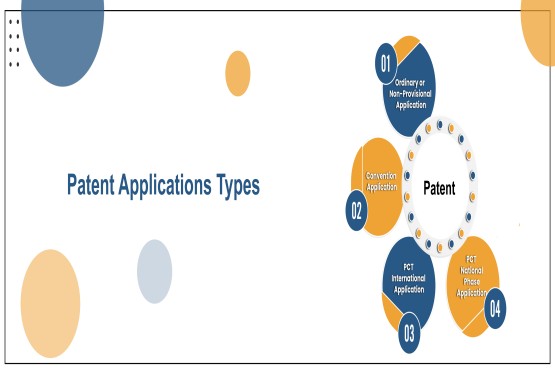
7. Patent portfolios may matter in technology-heavy businesses
For biotechnology, pharmaceuticals, engineering, hardware and certain technology businesses, patents may be closely connected to commercial value.
An investor may examine:
- applications and granted patents;
- ownership and assignment records;
- jurisdictions;
- filing and priority information;
- the relationship between the claims and the actual product;
- pending prosecution or objections; and
- material licensing
A patent can be commercially important, but the existence of a patent does not by itself prove that the business is free from every third-party IP risk.
8. Patentability and freedom to operate are different questions
Patentability asks, broadly, whether the startup's invention can satisfy the legal requirements for patent protection. Freedom to operate asks a different question: whether commercialising the product or process may create a risk of infringing third-party rights in the relevant jurisdictions.
A startup may have patentable technology and still need to investigate third-party rights. Conversely, a business can operate commercially without owning a patent of its own, depending on its technology and the rights of others. Investors may therefore distinguish between the strength of the startup's own IP and the risk arising from third-party IP.
9. Public disclosure can affect patent strategy
Investors may ask when an invention was developed, disclosed and filed. A startup may have published technical information, demonstrated a prototype, presented at a conference or otherwise disclosed an invention before filing. Depending on the facts and applicable law, earlier disclosure can create novelty or other patentability issues.
It would be inaccurate to say that every disclosure automatically destroys every patent possibility. The legal effect depends on the nature, timing and circumstances of the disclosure and any applicable statutory provisions. Nevertheless, investors may regard an unexplained disclosure history as an issue requiring further investigation.
10. Trademarks can be important even where patents are not
Consumer brands, e-commerce businesses, food companies, fashion businesses, media companies and service businesses may derive significant value from their brands.
An investor may therefore examine:
- the company name and product names;
- trademark applications and registrations;
- relevant classes;
- ownership;
- licensing arrangements;
- material objections or disputes; and
- possible conflicts with earlier
A startup that has invested heavily in a brand but has not considered conflicting trademark rights may face avoidable commercial risk.
11. Copyright can matter to technology and content businesses
Copyright may be relevant to:
- source code;
- website content;
- photographs;
- videos;
- graphics;
- manuals;
- marketing material; and
- other qualifying original
The investor may therefore want to know who created these works, who owns the relevant rights, and whether the company has sufficient rights to use and commercialise them. Registration is not a universal prerequisite for copyright protection in India, but ownership and contractual documentation can still be important in due diligence.
12. Open-source software is not automatically a problem
Many startups legitimately use open-source software. The issue is compliance with the applicable licence conditions. An investor may ask whether the startup knows which open-source components it uses and whether applicable obligations have been followed.
Depending on the licence and the way the software is used or distributed, obligations can vary. A startup should therefore maintain an appropriate software inventory and understand the licences applicable to important components.
13. Third-party licences can affect the value of the business
A startup may depend on licensed software, datasets, technology, content, photographs, APIs, fonts or other IP. An investor may examine:
- whether commercial use is permitted;
- duration;
- territory;
- transferability;
- sublicensing;
- termination; and
- change-of-control
A business that depends heavily on a non-transferable or easily terminable licence may carry a different risk profile from one that controls its core technology.
14. Confidential information and trade secrets require actual protection
Some startups rely less on registered rights and more on confidential know-how. Examples include algorithms, formulas, manufacturing processes, pricing strategies, customer information, supplier information, unpublished research and product roadmaps.
Calling something a “trade secret” does not, by itself, establish legal protection. Investors may therefore examine whether sensitive information is subject to confidentiality obligations, access controls and appropriate internal procedures.
15. IP disputes can create financial and operational risk
An unresolved IP dispute may involve litigation costs, injunction risk, licensing negotiations, product redesign, rebranding, settlement costs or disruption to commercial operations.
For an early-stage company, a dispute involving its core technology or brand can be particularly significant. Investors may therefore ask about actual, threatened or reasonably known IP claims and the company's response to them.
16. IP can affect scalability and imitation risk
Startup India identifies barriers to entry and imitation costs as relevant investment considerations. IP may contribute to those barriers, but IP is only one part of the picture.
A startup's defensibility may also arise from network effects, customer relationships, regulatory approvals, distribution, data advantages, manufacturing capability, brand recognition or contractual arrangements. Therefore, the absence of a patent does not automatically mean that a startup lacks a competitive advantage.
17. IP may affect valuation—but there is no simple “patent = valuation” formula
IP can contribute to the commercial value of a startup, but its value is highly context-dependent. An investor may consider:
- relevance of the IP to revenue;
- scope and strength of rights;
- remaining term where applicable;
- market relevance;
- ownership;
- enforceability;
- licensing potential;
- competing technology; and
- associated legal
A patent registration should therefore not be presented as having a fixed monetary value simply because it exists. Startup India separately identifies valuation as an investment consideration and lists multiple approaches to startup valuation.
18. Investors may compare the IP position with the pitch deck
Suppose a pitch deck states:
“We own proprietary AI technology.”
An investor may reasonably ask what “proprietary” means. It could refer to source code, a patent application, confidential know-how, a dataset, an algorithm, licensed technology or simply a product architecture developed by the startup.
The point of due diligence is not to assume that a marketing statement is legally accurate. It is to test important claims against supporting documents and facts. Startup India describes investor due diligence as a process through which investor claims and business information are examined before an equity deal is finalised.
19. IP can matter to licensing and future transactions
A startup may later license technology, enter strategic partnerships or be acquired. Clear ownership and well-drafted licences can make these transactions easier to assess.
An investor may therefore look beyond the immediate funding round and consider whether the startup's IP can be transferred, licensed or otherwise commercialised without unexpected restrictions.
20. IP matters in an eventual exit
Potential acquirers may conduct their own legal due diligence. If a startup's core software belongs partly to a founder, its brand is disputed, or critical technology is subject to an uncertain licence, those issues can become relevant during a later acquisition.
Startup India identifies potential future acquirers and alliance partners as an exit consideration for investors. IP is therefore relevant not only to the present investment but also to the possibility of a future transaction.
21. What may be included in an IP due-diligence file?
The precise document request depends on the transaction, but a startup may prepare:
PATENTS
- applications and granted patents;
- assignment documents;
- material prosecution records;
TRADEMARKS
- applications and registrations;
- assignment or licence documents;
- material objections or
COPYRIGHT AND SOFTWARE
- relevant ownership or assignment documents;
- development agreements;
- third-party licences;
- open-source
CONFIDENTIALITY
- NDAs;
- relevant employment or consultancy provisions;
- internal confidentiality policies where
DISPUTES
- material infringement notices;
- opposition proceedings;
- litigation;
- settlement
The purpose is to provide a coherent picture of what the company owns, uses and may be exposed to.
22. A clean IP file does not guarantee funding
A startup with clear IP ownership and documentation may reduce one category of uncertainty. But investment decisions are broader than IP. Startup India identifies factors including market landscape, scalability, customers and suppliers, competition, sales and marketing, financial assessment, management and exit avenues.
Therefore, good IP does not guarantee investment. Likewise, the absence of a large patent portfolio does not automatically make a startup unsuitable for investment. The importance of IP depends on the startup's sector, stage, technology and business model.
23. What founders should do before approaching investors
Before a funding round, founders should:
- Identify the startup's material IP
- Confirm who owns each important
- Document founder-to-company transfers or licences where
- Review employee, consultant and freelancer
- Check patent and trademark
- Review third-party
- Maintain an open-source software inventory where
- Identify material disputes or
- Review confidentiality
- Ensure that statements in the pitch deck can be supported by
The objective is not to create an enormous IP portfolio simply for fundraising. The objective is to know exactly what the startup owns, what it uses, and where the material legal risks lie.
Conclusion
Investors examine intellectual property because IP can affect ownership, competitive advantage, commercial freedom, litigation exposure, licensing opportunities, valuation considerations, scalability and future transactions.
But the real question is not:
“Does the startup have a patent?”
It is:
“Does the startup own or have sufficient rights to use the intellectual assets on which its business depends, and can it demonstrate that position?”
For founders, IP due diligence should therefore begin before the investor asks for the documents.
A startup that identifies its important IP, documents ownership, manages third-party rights, protects confidential information and accurately describes its IP position is better prepared to answer investor questions and address legal issues before they become transaction problems.
Ultimately, investors are not simply examining what a startup has created. They are examining what the startup can legally own, control, protect and commercially exploit.